Decision Wheel
Decision maker
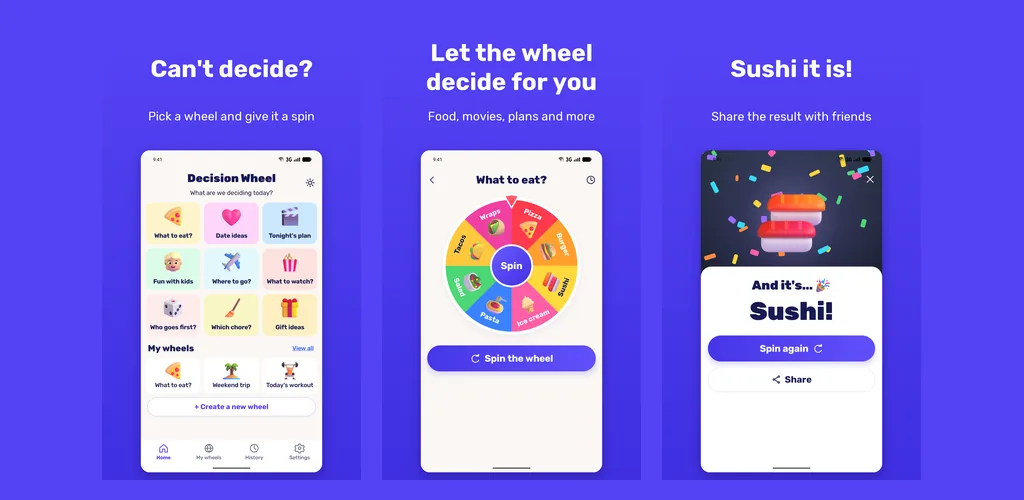
Can't decide what to eat or who goes first? Pick a ready made wheel or build your own, then spin.
Money · Android
Add your debts and see the month you'll be debt free. Then switch between the snowball and avalanche methods and see which one costs you less interest. There's no account, no bank login and no ads.
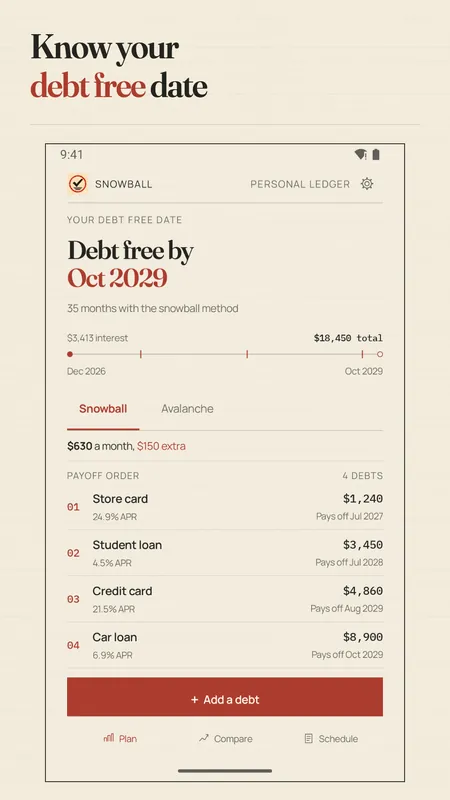
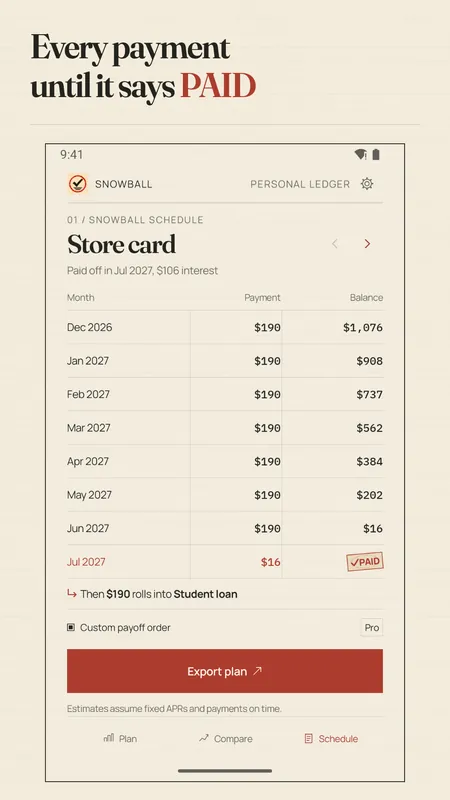
You type in each debt with its balance, APR and minimum payment, then pick how much you can pay each month on top of the minimums. The planner puts that extra money on one debt at a time. When a debt is paid off, its payment rolls into the next one, so the amount you pay each month keeps working until everything is gone.
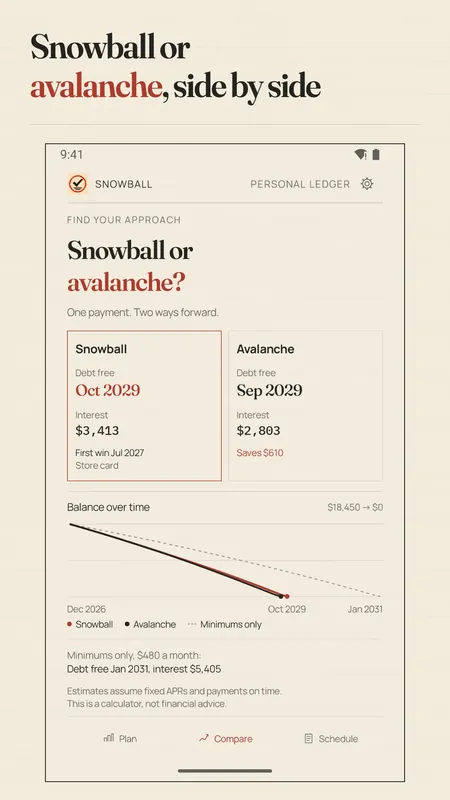
The Compare tab puts both side by side: the debt free month, the total interest, and the difference between them.
The example inside the app has four debts: a store card, a student loan, a credit card and a car loan, $18,450 in all, with $150 a month on top of the minimums. With the snowball method you're debt free in October 2029 and pay $3,413 in interest. The avalanche finishes a month sooner, in September 2029, and costs $2,803. Paying only the minimums would take until January 2031 and cost $5,405.
The avalanche saves money, and the snowball gives you an early win, since the store card is gone in July 2027. Which one keeps you going is up to you, and the app shows you both before you choose.
You can run the same example in your browser with the debt snowball vs avalanche calculator on this site. It uses the same math as the app.
The planner is free for up to 5 debts, with both methods and the full schedule. A one time Pro purchase of $4.99 adds saved plans, a side by side comparison of different plans, your own custom payoff order and unlimited debts. There are no ads in either version and no subscription.
No. There's no account and no bank login. You type in your balances yourself, and everything stays on your phone.
It's a close estimate. The math uses monthly interest on fixed APRs and assumes every payment is made on time. Real lenders can round or charge interest a little differently, so treat the dates as a close estimate rather than a promise.
The avalanche usually pays less interest. The snowball clears a debt sooner, which some people find easier to stick with. Look at both in the Compare tab and pick the one you'll actually follow.
No. It's a calculator that runs your numbers. For advice on your situation, talk to a qualified adviser or a nonprofit credit counselor.
Can't decide what to eat or who goes first? Pick a ready made wheel or build your own, then spin.
Pick a week or draw an envelope, tap to save and watch the jar fill up. Do 52 weeks, 100 envelopes or your own goal.
A feet, inch and fraction calculator that keeps exact fractions. Pro adds stairs, rafters, concrete and six more tools for $6.99 once.